

 GIFT City Funds
The charge is interest, not a flat fee. Finance charges in credit card appear when the full bill is not paid by the due date.
Quick Answer Box
Finance Charges Interest on Revolving Balances or Cash Advances. Cards in India are often quoted at 2.5-4 per cent per month (or about 30-48 per cent annualised). The calculation of interest is done daily. If you only pay the minimum, you usually lose the interest-free period and interest can run from the date of the transaction. The simplest way to avoid purchase finance charges is to pay the full statement balance by the due date. Rates vary from card to card. There is no official “lowest” list.
What Finance Charges Are and How They Are Calculated
What are credit card finance charges? What are Finance Charges on Credit Cards and How are They Calculated?
They are the interest the bank charges you for keeping a balance past the due date or for a cash withdrawal. The MITC (Most Important Terms and Conditions) of the card mentions the rate per month and the method.
Typical calculation (daily balance method used by most Indian issuers):
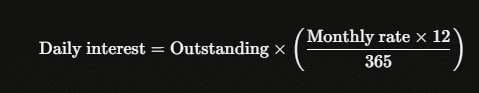
Sum the daily interest for the days the balance was outstanding, then add 18 percent GST on In most cases, you add up the daily interest for the days the balance was outstanding, then add 18 percent GST on the finance charge.
Key rules of surprising people:
- Usually, if you pay the full statement balance by the due date, you have an interest-free grace period on purchases from that cycle (often 20-50 days from the transaction to the due date).
- If you pay less than the full balance due or only the minimum amount due, you will lose the interest-free period. As a rule, interest is charged on the unpaid amount from the date of each transaction (RBI has directed that interest should be on the outstanding portion; some issuers’ older practices charged on the full amount until payment—check your MITC).
- If a prior balance is rotating, new buys may also start to accrue interest.
- Cash advances (ATM withdrawals on the card) almost never have any grace period. Interest starts from the date of withdrawal and there is a separate cash advance fee.
Same logic applies for hdfc credit card financial charges. HDFC (and other issuers) publish card specific monthly rates for MITC. The rates vary by variant. A premium card may have a lower rate than a mass-market card from the same bank. The number on your own MITC is the applicable one.
What interest rate is used to calculate finance charges on credit cards?
Across Indian issuers, the monthly rate is often in a range of about 2.5 percent to 4 percent. That is an annualized return of about 30-48% before GST. Some cards are lower, some are higher. RBI disclosures as required. There is no statutory ceiling. A consumer forum’s move to fix rates was quashed. Always read the MITC of the particular card to be sure.
How Finance Charges Affect the Outstanding Balance
Then the finance charge (and GST) is added to the amount you owe. If you don’t pay off the new total by the next due date, interest is charged on the higher amount. That’s how a small unpaid can snowball fast. Many times, minimum-due payments cover only interest and fees, so the principal decreases slowly.
For example, an unpaid ₹50,000 at 3.5 percent per month for 30 days attracts a hefty interest amount, excluding GST. Interest is usually levied on the outstanding amount from the date of the transactions, even if you pay ₹49,000 and leave ₹1,000 unpaid, and not merely on the ₹1,000 from the due date.
How to Avoid Them
How can I avoid finance charges on my credit card bills?
- Pay off the full statement balance by the due date each month. This is the only safe way for normal buyings.
- Don’t take cash advances unless you agree to the fee and immediate interest.
- If you’ve done the revolutions, pay as much as you can as soon as you can. Interest is charged daily.
- Set up a standing instruction or calendar reminder for the full amount.
- If you are really cash strapped, a personal loan or planned EMI conversion (where offered) can sometimes be cheaper than revolving at card rates but do compare the total cost.
- Only negotiate a rate decrease after you have a repayment plan. If you revolve, a lower rate still compounds.
Which credit cards offer the lowest finance charges in India?
There is no official ranking or RBI list of ‘lowest’. Rates are card specific and subject to change. An advertized lower rate is only of use if you intend to revolve. For most people, a card with rewards you’ll actually use, combined with the habit of paying in full, is the better design. A generic “lowest” list is less useful than comparing the MITCs of two or three cards you already qualify for.
Financial & Technical Data Matrix – When Interest Starts
| Action | Interest-free period | Finance charge |
| Pay full balance by due date | Normally yes on purchases | None on those purchases |
| Pay only minimum or partial | Lost | From transaction date on unpaid (check MITC) |
| Cash advance | None | From withdrawal date + fee |
| New purchase while revolving | Usually lost | Can start immediately |
Risk Analysis: Eleven Finance-Charge Errors
- Paying only the minimum and expecting no interest.
- Assuming interest starts only after the due date.
- Leaving a small unpaid amount and thinking interest applies only to that sliver from the due date.
- Taking a cash advance for “a few days.”
- Ignoring GST on the finance charge.
- Treating a reward-rate comparison as more important than the revolving rate you will actually pay.
- Believing there is an RBI cap that protects you.
- Not reading the MITC of your specific card (HDFC or any other).
- Letting finance charges compound for several cycles.
- Using a third-party “lowest interest” list that is outdated.
- NRIs or travellers assuming the same grace-period rules on every international transaction.
Generic Advice vs. Strategic Thinking Matrix
| Decision Point | Generic Advice | Strategic Thinking |
| Avoid interest | “Pay minimum” | Pay full statement balance by due date |
| Rate | “Find the lowest card” | Read your MITC; pay in full |
| Partial pay | “Interest only on the leftover” | Grace period usually lost; check from transaction date |
| Cash advance | “Convenient” | Immediate interest + fee |
| Effect on balance | “Small charge” | Added to principal and can compound |
Strategic thinking treats the due-date full payment as the default, not the exception.
Closing Perspective
Finance charges are daily interest on unpaid credit card balances that are high. The Indian rates are several percentage points a month; If you don’t pay the full statement balance by the due date, you’ll normally lose the interest-free period. Interest on cash advances begins immediately. The charge will be added to your bill. There’s no official lowest-rate ranking. What matters is your card’s MITC and your habit of full payment.
This is general information, not a recommendation to revolve a balance or select any particular card.
People Also Ask
What are finance charges on a credit card?
The interest charged when you do not pay the full statement balance by the due date, or on cash advances.
How are they calculated?
Usually daily on the outstanding balance at the card’s monthly rate converted to a daily rate, plus GST.
What is a typical rate in India?
Commonly about 2.5–4 percent per month. The exact rate is in your card’s MITC.
How do I avoid them?
Pay the entire statement balance by the due date. Avoid cash advances.
Do they apply if I pay most of the bill?
Yes. Paying less than the full amount normally loses the interest-free period.
How do they affect my balance?
They are added to the outstanding amount and can themselves attract further interest.
Which card has the lowest finance charges?
There is no official list. Rates vary by issuer and card. Paying in full matters more than the headline rate.
How can WealthMunshi help?
WealthMunshi provides financial-planning support on revolving-debt cost and repayment structure, not as a card issuer.
A minimum-due payment keeps the card active and starts the interest clock. Readers who have begun to revolve a balance can schedule a cost-and-repayment review before the next cycle’s finance charge is added.